

Blogs
Executive Summary: Navigating the Pea Starch Market in 2026 and Beyond
The global pea starch market has entered a decisive inflection point. Between 2020 and 2025, the industry expanded from $107.0 million to an estimated $165.0 million in annual revenue, reflecting a compound trajectory that underscores shifting consumer preferences, formulation innovation, and supply chain realignment across multiple verticals. As we look toward the forecast window of 2026 through 2032, the market is projected to reach $288.0 million, sustained by a long-term growth rate of 8.4 percent. These figures are not merely statistical markers; they represent a structural reallocation of ingredient strategies across food and beverage, animal feed, and industrial applications.
OBC+DC/DC Integrated On-board Charger Market
This strategic overview is designed to equip decision-makers with the contextual intelligence required to navigate an increasingly competitive landscape. The purpose of this piece is to preview the analytical architecture of our newly released Pea Starch Market research report while demonstrating the depth of insight available to subscribers. Rather than offering a superficial scan of surface-level trends, the full study dissects the operational, regulatory, and competitive forces that will shape procurement strategies, product development roadmaps, and market entry decisions throughout the remainder of the decade.
UHPLC Packing Materials Market
The following sections outline the macro trajectory, segmentation dynamics, competitive positioning, and regulatory environment that define the current market moment. Where granular breakdowns, regional weightings, and proprietary scenario models are required for precise planning, this preview intentionally withholds the exact figures and segment allocations. Those data points are embedded within the full report and structured to support direct integration into corporate forecasting workflows.
Wafer Grade Micro Lens Array (MLA) Market
Market Trajectory and Growth Architecture
The revenue arc from 2020 to 2025 demonstrates consistent acceleration, with year-over-year expansion reflecting both volume growth and value migration toward higher-functioning starch formats. The 2025 baseline of $165.0 million sets the stage for a forecast period in which incremental gains are expected to compound at a measured but persistent pace. By 2026, the market is anticipated to reach $180.06 million, and the climb continues through 2027 at $199.09 million, 2028 at $203.01 million, and 2029 at $226.94 million. The latter half of the forecast horizon shows further expansion toward $244.0 million in 2030, $272.54 million in 2031, and $288.0 million in 2032.
Several structural drivers underpin this trajectory. First, the clean-label movement continues to reshape ingredient specifications across categories where native starches and modified starches must satisfy both functional performance and consumer transparency expectations. Second, the expansion of plant-based and gluten-free product lines has elevated pea starch from a niche texturizer to a mainstream formulation backbone. Third, industrial and animal feed applications are incorporating pea-derived inputs at increasing rates as processors seek alternative carbohydrate sources that align with sustainability targets and supply diversification strategies.
Our full report decomposes this growth into forward-looking scenarios that account for pricing volatility, raw material availability, processing yield improvements, and regional demand shifts. Rather than presenting a single linearized forecast, the analysis provides a range of outcomes tied to plausible macroeconomic and supply-side conditions, enabling procurement and strategy teams to model exposure and opportunity with greater precision.
Segmentation Dynamics: Type, Application, and Regional Balance
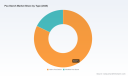
The market is organized around two principal product categories: native pea starch and modified pea starch. Native formats continue to command the larger revenue share, reflecting their broad compatibility with clean-label positioning, straightforward processing requirements, and established demand in food and beverage formulations. Modified variants, while smaller in absolute terms, are gaining traction in applications that require enhanced stability, textural control, or thermal solubility without sacrificing label simplicity. The interplay between these two categories is a central theme of the report, particularly as manufacturersExperiment with hybrid formulations and process innovations that blur the traditional boundary between native and modified performance profiles.
In terms of end-use, food and beverage applications represent the largest demand pool, followed by animal feed and industrial applications. The food and beverage segment benefits from continuous reformulation activity, especially in baked goods, confectionery, dairy alternatives, and plant-based meat analogues, where pea starch contributes to texture, moisture retention, and clean-label ingredient decks. Animal feed applications leverage pea starch as a functional carbohydrate source within optimized nutrition formulations, while industrial uses span adhesives, coatings, and specialty processing aids that require predictable viscosity and binding characteristics.
Regional demand is distributed across multiple geographies, with mature markets in North America and Europe maintaining strong consumption bases, while Asia Pacific, Latin America, and the Middle East and Africa contribute increasingly important growth nodes. The full study maps these regional profiles without reducing them to static share percentages, instead focusing on the drivers that differentiate demand intensity, procurement patterns, and distribution infrastructure across each territory. This approach allows strategists to identify where near-term volume opportunities are most concentrated and where longer-term capacity investments may yield competitive advantage.
To preserve the analytical value of the segmentation exercise, the report avoids publishing exhaustive sub-segment figures in public summaries. Instead, it provides structured frameworks that show how type, application, and regional variables interact, along with the conditions under which share shifts are most likely to occur. Subscribers gain access to the complete allocation tables, sensitivity analyses, and scenario overlays needed to translate these dynamics into operational plans.
Competitive Landscape: Eight Profiles and the Shape of Rivalry
The pea starch market is characterized by a moderately concentrated competitive structure. The three-firm concentration ratio stands at 42.0 percent, while the five-firm concentration ratio reaches 52.0 percent. This configuration suggests a market in which a core group of established producers commands a substantial portion of revenue, yet sufficient fragmentation remains to allow specialist players, regional suppliers, and innovation-driven entrants to compete on formulation quality, sustainability credentials, and customer-specific service models.
Several companies illustrate the strategic diversity shaping the market. Roquette Frères, headquartered in Lestrem, France, produces both native and modified pea starch, including the AMYSTA™ L 123 label-friendly thermally soluble pea starch and organic pea starch for food, nutraceutical, and confectionery applications. Ingredion Incorporated, based in Westchester, Illinois, USA, offers PURITY® P native pea starch and HOMECRAFT Pulse PG 100 for clean-label texturizing in baked goods, gluten-free products, and plant-based applications. Emsland Group, located in Lingen, Germany, manufactures native and modified pea starch from yellow peas for food, pet nutrition, and industrial uses with clean-label profiles.
Cosucra Groupe Warcoing, based in Warcoing, Belgium, produces NASTAR™ native pea starch and pre-gel instant pea starch for food ingredients with a sustainability focus. The Scoular Company, headquartered in Omaha, Nebraska, USA, supplies premium pea starch from yellow peas for food manufacturing, pet food, and plant-based formulations with gluten-free and clean-label properties. Vestkorn Milling AS, in Vestfold, Norway, is a leading European producer of pea starch and concentrates from dry and wet processing for food and industrial applications. Nutri-Pea Limited, in Portage la Prairie, Manitoba, Canada, is a North American manufacturer of pea starch and functional ingredients from Canadian yellow peas with local sourcing. PURIS, based in Dawson, Minnesota, USA, produces upcycled pea starch in North America for alternative meats, supplements, and clean-label food applications.
These profiles point to a competitive environment where differentiation is increasingly tied to processing technology, label compatibility, regional sourcing advantages, and the ability to serve adjacent verticals such as pet nutrition and nutraceuticals. The report evaluates each company’s product architecture, geographic footprint, and strategic posture, then situates them within a broader rivalry map that highlights where consolidation pressure, capacity expansion, or technology-led disruption is most probable. Rather than offering a simple ranking, the analysis clarifies the competitive levers available to each player and the conditions under which market share may migrate.
Recent Developments and the Innovation Signal
Product innovation remains a powerful indicator of where the market is heading. In October 2025, Roquette Frères introduced AMYSTA™ L 123, described as the first label-friendly thermally soluble pea starch using an enzyme- and chemical-free process for clean-label beverages, soups, and sauces. This launch is significant not only for the product itself but for what it signals about the industry’s direction: a growing emphasis on thermal solubility, label simplicity, and process cleanliness in categories where formulation transparency is a decisive purchasing criterion.
The introduction of such a solution expands the functional envelope of pea starch in liquid and semi-liquid applications, potentially accelerating adoption in beverage and sauce formulations that previously relied on more complex starch modification or non-pea inputs. It also illustrates how leading suppliers are investing in process engineering to reconcile performance requirements with clean-label expectations, a tension that continues to shape product development across the category.
The full report examines this launch within a wider set of recent developments, connecting product-level moves to broader strategic implications for formulation teams, procurement managers, and competitors evaluating whether to follow with comparable offerings. By mapping the innovation pipeline against demand patterns and regulatory context, the study helps organizations anticipate where functional gaps may close, where substitution risk may rise, and where first-mover advantages can be sustained.
Regulatory Tailwinds and the Efficiency Imperative
Regulatory activity is adding a new layer of strategic relevance to pea starch processing and industrialization. Commission Implementing Regulation (EU) 2026/916 of 27 April 2026 amends Implementing Regulation (EU) 2025/2144 to support research and industrialization for improving pea starch separation efficiency using indigenous lactic acid. This development underscores a policy environment that encourages process optimization, resource efficiency, and technological upgrading within the value chain.
For manufacturers and downstream users, the practical implication is that separation efficiency gains may translate into cost structure improvements, yield stability, and reduced processing complexity over time. It also suggests that regulatory frameworks are increasingly aligned with industrial goals that favor higher-utilization feedstocks and cleaner processing routes. In a market where margins can be sensitive to raw material availability and processing economics, such policy-supported efficiency improvements can influence competitive positioning and capacity planning.
The report integrates this regulatory context into a broader discussion of market dynamics, linking policy signals to operational variables such as capital investment timing, technology adoption curves, and regional competitiveness. By tracing how regulation interacts with innovation and supply-side economics, the study provides a more complete picture of the forces that will shape industry profitability and structural change through the forecast period.
What the Full Report Delivers: Actionable Intelligence for 2026 Decision-Making
The public preview above is intended to demonstrate the analytical rigor and strategic relevance of the full Pea Starch Market research study. Subscribers receive a comprehensive, decision-oriented package that moves beyond high-level description into the operational specifics required for planning, sourcing, and competitive positioning.
The report includes detailed segmentation analysis that breaks down type, application, and regional demand patterns with the granularity needed to support product planning and market-entry evaluation. It provides historical trend reconstruction from 2020 through 2025 alongside the 2026–2032 forecast, enabling users to benchmark current performance against projected trajectories and identify inflection points. Competitive profiling extends beyond company summaries to include strategic posture assessment, product architecture mapping, and scenario-based share dynamics.
In addition, the study incorporates market concentration metrics and interprets their implications for pricing behavior, capacity utilization, and partnership strategy. It examines demand-side drivers across food and beverage, animal feed, and industrial applications, with attention to formulation trends, clean-label requirements, and cross-category substitution risk. Regulatory developments are analyzed for their potential impact on processing efficiency, supply economics, and regional competitiveness.
Strategically, the report is designed to support multiple decision contexts. For procurement teams, it offers a structured basis for evaluating supplier options, anticipating cost and availability shifts, and aligning sourcing strategies with formulation roadmaps. For product development organizations, it clarifies where functional demand is expanding and which starch formats are best positioned to meet emerging label and performance requirements. For corporate strategists and investors, it maps concentration dynamics, innovation signals, and regulatory tailwinds to identify where value creation is most likely to accrue over the forecast horizon.
Crucially, the full study reserves its most decision-sensitive data for subscribers, including the complete segmentation allocations, regional detail, and scenario overlays that cannot be responsibly summarized without losing analytical precision. This design ensures that the report functions as a practical planning tool rather than a general market overview, giving organizations the specific intelligence needed to act with confidence in 2026 and beyond.
Strategic Imperatives for the Next Planning Cycle
As the market moves from $165.0 million in 2025 toward $288.0 million by 2032, the strategic question is not whether pea starch will continue to gain relevance, but how companies should position themselves to capture value amid intensifying competition, evolving formulation standards, and regulatory-supported efficiency gains. Organizations that treat pea starch as a static commodity input risk underpricing its strategic importance in clean-label, plant-based, and diversified supply-chain strategies. Organizations that invest in formulation alignment, supplier partnership quality, and process-aware procurement are better positioned to convert market growth into durable advantage.
The competitive map suggests that differentiation will increasingly depend on the ability to deliver label-friendly functionality, thermal solubility where needed, and reliable supply from transparent sourcing bases. Concentration metrics indicate that while a core group of producers holds substantial market weight, the presence of multiple capable players creates both partnership opportunities and substitution risks. Recent innovation signals and regulatory developments point to a market in which processing efficiency and clean-label compatibility are moving from desirable attributes to essential requirements.
For decision-makers preparing for the 2026 planning cycle, the immediate priority is to ground strategy in a clear view of where demand is expanding, which product formats are gaining traction, and how competitive and regulatory forces are likely to reshape supply economics. The full Pea Starch Market report provides that view in a structured, forecast-linked format designed for direct use in commercial planning, procurement strategy, and product development decision-making.
This preview has outlined the market’s macro trajectory, segmentation logic, competitive structure, innovation direction, and regulatory context to demonstrate the depth of analysis available in the complete study. The specific figures, segment allocations, and scenario models that enable precise planning are reserved for the full report, where they are presented in a form that supports actionable interpretation rather than passive reading. Organizations that engage with the full dataset will be better equipped to anticipate shifts, allocate resources, and build formulations and sourcing strategies that align with the market’s next phase of growth.
For detailed analysis of this topic, please visit the official page: Pea Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Acoustic Wave Sensor Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific acoustic wave sensor market was valued at USD 755 Million in 2020 and has exhibited robust growth, reaching USD 1,430 Million by 2025. Consistent innovation and adoption in automotive, healthcare, and industrial automation sectors have powered this double-digit CAGR. The revenue trend remains upward through 2035, with forecasts suggesting USD 5,020 Million as developers leverage advancements in MEMS technology and expand into new IoT and smart city use cases.
Read More - https://bussinessinsights.com/research-report/asia-pacific-acoustic-wave-sensor-market
The automotive sector represents the largest share in application, propelled by regulatory mandates for TPMS and advanced driver assistance systems. Healthcare follows closely due to expanding uses in biosensing and medical diagnostics. Consumer electronics ranks third as wearable devices and IoT applications proliferate. Industrial automation and environmental monitoring are experiencing robust year-on-year growth, driven by Industry 4.0 investments and smart factory initiatives, while military & defense continues to sustain steady demand for high-reliability, passive sensor technologies.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-acoustic-wave-sensor-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Acoustic Wave Sensor Market industry?
The top 5 players in the Asia-Pacific Acoustic Wave Sensor market are Siemens AG, Murata Manufacturing Co., Ltd., Honeywell International Inc., Kyocera Corporation, and Teledyne Technologies. These companies are known for their innovation and broad product portfolios, spanning applications in automotive, industrial, and healthcare sectors.
What is the Asia-Pacific Acoustic Wave Sensor Market growth?
The Asia-Pacific Acoustic Wave Sensor Market is witnessing robust growth, driven by increasing adoption in consumer electronics and automotive sectors. For instance, Murata Manufacturing announced expanded investments in acoustic sensor production in 2023 to meet rising demand in connectivity and safety applications.
Which segment accounted for the largest Asia-Pacific Acoustic Wave Sensor Market share?
The automotive application segment accounted for the largest market share in the Asia-Pacific Acoustic Wave Sensor Market. Rapid advances in vehicle safety, infotainment, and emission control systems have drastically increased the integration of acoustic wave sensors by leading automotive manufacturers in the region.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Track Geometry Measurement System Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific TGMS market displays a strong upward revenue trajectory, reflecting ongoing rail infrastructure development and technological convergence. Market size reached $1,320 Million in 2025, propelled by government investments and private sector participation. By 2035, revenues are projected to grow at a CAGR of 9.8%, surpassing $3,380 Million. The rise is attributed to increased adoption of digital rail solutions, new metro and high-speed rail projects, and the proliferation of no-contact systems. Consistent expansion in Southeast Asian and Pacific nations further bolsters the revenue outlook, making the region a global growth hotspot.
Read More - https://bussinessinsights.com/research-report/asia-pacific-track-geometry-measurement-system-market
Railway track applications account for the largest market share in 2025, as national railways and metro operators invest in regular monitoring to improve safety and performance. Metro track applications follow, fueled by rapid urbanization and new metro projects in major APAC cities. High-speed rail track measurement is the fastest-growing segment as countries like China and Japan expand high-speed networks. Heavy haul, light rail, and others represent niche yet essential use cases, particularly in resource-centric economies. TGMS deployment is now considered a core operational requirement for most major rail infrastructure programs.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-track-geometry-measurement-system-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Track Geometry Measurement System Market industry?
The top five players in the Asia-Pacific Track Geometry Measurement System Market include Amberg Technologies, Trimble Inc., Fugro, Ensco, and MERMEC Group. These companies offer advanced rail track inspection solutions, leveraging innovative technologies and comprehensive service portfolios to serve rail operators, infrastructure owners, and government agencies across the Asia-Pacific region.
What is the Asia-Pacific Track Geometry Measurement System Market growth?
The Asia-Pacific Track Geometry Measurement System Market has experienced significant growth, driven by rapid rail infrastructure expansion and modernization projects. For instance, Trimble Inc. witnessed increased adoption of its rail solutions in 2023, aligning with government investments in smart transportation systems and stringent track safety requirements across countries like China, India, and Japan.
Which segment accounted for the largest Asia-Pacific Track Geometry Measurement System Market share?
The largest market share is held by the conventional railway applications segment. This dominance is due to extensive rail network upgrades and frequent inspections needed for passenger and freight routes. The demand for safety, operational efficiency, and reduced maintenance costs has led operators to adopt sophisticated geometry measurement solutions in conventional railways.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific eye tracking market is forecasted to demonstrate strong growth from 2020 to 2035, with market revenue rising from USD 305 Million in 2020 to an estimated USD 560 Million in 2025 and reaching USD 1,020 Million by 2035. The majority of the expansion is attributed to the widespread integration in automotive safety systems, healthcare diagnostics, and the proliferation of AR/VR consumer applications. The compound annual growth rate (CAGR) is expected to be 17.2% over the forecast period. Investments in AI-driven analytics, portable platforms, and regulatory support for accessibility are key revenue drivers, solidifying Asia-Pacific as a growth engine in the global eye tracking ecosystem.
Read More - https://bussinessinsights.com/research-report/asia-pacific-eye-tracking-market
Research applications lead the Asia-Pacific eye tracking market in 2025, accounting for 36% of the total share, propelled by demand in academic, neurological, and consumer behavior studies. Human-computer interaction (HCI) captures 28%, closely followed by assistive technology at 18%. Automotive safety and driver monitoring contribute 10%, while consumer devices hold an 8% share. The sector's dominance in research is a testament to the technology's value in understanding cognitive processing and behavior. Meanwhile, HCI and assistive technologies benefit from rapid tech adoption in education, enterprise, and healthcare. As awareness grows and deployment costs drop, the spread of eye tracking into UX, AR/VR, and daily-use devices is expected to further transform user experience and inclusivity across APAC.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-eye-tracking-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Eye Tracking Market industry?
The top 5 players in the Asia-Pacific Eye Tracking Market include Tobii AB, SR Research, Seeing Machines, EyeTech Digital Systems, and Smart Eye AB. These companies are recognized for their advanced technology, comprehensive product portfolios, and significant regional presence, contributing to the widespread adoption of eye tracking solutions in various sectors.
What is the Asia-Pacific Eye Tracking Market growth?
The Asia-Pacific Eye Tracking Market has shown robust growth, driven by increasing adoption across healthcare, automotive, and research sectors. For instance, in 2023, Smart Eye AB reported a surge in demand for its driver monitoring systems, highlighting the region’s accelerated technological advancements and investment in human-computer interaction technologies.
Which segment accounted for the largest Asia-Pacific Eye Tracking Market share?
The research and healthcare application segment holds the largest share in the Asia-Pacific Eye Tracking Market. Eye tracking is extensively used for psychological studies, neuromarketing, and medical diagnostics, as demonstrated by the growing partnerships between academic institutions and solution providers such as Tobii AB.
Thanks & Regards,
Priya
sales@bussinessinsights.com
PW Consulting: Instant Adhesive Market to Hit $344.8M by 2032, 6.58% CAGR Amid 2025's $215M Growth
By PW Consulting, 2026-09-07
Projecting the Instant Adhesive Market: A Strategic Blueprint for 2026 and Beyond
Introduction: The Adhesive Imperative in Modern Manufacturing
In the contemporary industrial landscape, bonding technologies have evolved from simple assembly aids to critical engineering components that dictate product performance, durability, and design flexibility. The instant adhesive market stands at the forefront of this transformation, serving as an essential enabler across sectors ranging from high-precision electronics to heavy-duty transportation manufacturing. As organizations navigate an increasingly complex global environment characterized by supply chain recalibrations, stringent environmental regulations, and shifting consumer expectations, the ability to make informed, data-driven decisions regarding adhesive procurement and investment has never been more vital.
Escape Door Control Unit Market
This comprehensive market research study examines the historical trajectory and future projections of the instant adhesive industry, offering a rigorous analytical framework designed to support executive decision-making through 2032. By synthesizing macroeconomic trends, competitive intelligence, raw material dynamics, and regulatory pressures, this report provides stakeholders with the actionable intelligence needed to position their organizations advantageously in a market projected to experience sustained growth.
Gasket Structure Keyboard Market
Market Trajectory: Navigating Growth Amid Volatility
The instant adhesive market has demonstrated remarkable resilience and expansion over the past half-decade, establishing a robust foundation for continued momentum. Historical data from 2020 through 2025 reveals a market that has not only recovered from disruptions but has accelerated its growth trajectory, reaching approximately 215.0 Million USD in the base year of 2025. This represents a significant evolution from the 163.15 Million USD recorded in 2020, underscoring the compound annual growth rate that has characterized the industry's maturation.
Worldwide Switch Expansion Joints (SEJ) Market
Looking ahead, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 6.58 percent, a figure that reflects both steady demand expansion and the industry's capacity to adapt to emerging technological and regulatory requirements. By 2026, market revenue is anticipated to reach 230.33 Million USD, climbing progressively to 344.8 Million USD by the close of the forecast horizon in 2032. This upward trajectory signals more than mere volume growth; it indicates a maturing market where value creation is increasingly tied to product innovation, application-specific formulations, and strategic geographic expansion.
Several structural factors underpin this growth outlook. The ongoing transition toward lightweight materials in transportation and automotive manufacturing continues to drive demand for high-performance bonding solutions that can replace traditional mechanical fasteners. Simultaneously, the electronics industry's relentless miniaturization and the medical sector's push for biocompatible, rapid-curing adhesion technologies create sustained pull factors across multiple end-use verticals. Companies that recognize these cross-industry demand signals and align their product development pipelines accordingly will be best positioned to capture disproportionate market share in the coming years.
Structural Composition: Demand Drivers Across Key Verticals
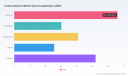
Understanding where instant adhesive demand concentrates is essential for strategic resource allocation and market entry timing. The application landscape reveals a diverse but clearly hierarchical set of consumption patterns that reflect broader industrial trends. Electronics represents a dominant consumption segment, driven by the sector's need for precise, high-speed bonding in component assembly, consumer devices, and increasingly sophisticated wearable technologies. The woodworking sector, while historically associated with slower-curing formulations, has embraced instant adhesive solutions for applications requiring rapid turnaround and strong initial tack in furniture manufacturing and cabinetry production.
Transportation applications continue to expand as original equipment manufacturers seek weight-reduction strategies and design flexibility that instant adhesives facilitate. This includes both traditional automotive manufacturing and the rapidly growing electric vehicle segment, where battery assembly and lightweight structural components demand specialized bonding chemistries. The medical sector represents another critical growth vector, with demand fueled by surgical device assembly, wound closure applications, and the development of increasingly sophisticated diagnostic equipment. Industrial applications broadly encompass manufacturing assembly, maintenance repair operations, and specialty bonding tasks that require rapid setting times without compromising ultimate bond strength.
From a product type perspective, the market is anchored by two principal categories. Cyanoacrylate-based instant adhesives command the largest share of the product landscape, reflecting their widespread adoption across consumer, industrial, and medical end uses due to their rapid curing characteristics and strong bonding performance on a variety of substrates. Epoxy-based instant adhesive formulations constitute a complementary segment, particularly valued in applications requiring higher temperature resistance, greater structural integrity, or specialized chemical resistance profiles. The interplay between these product categories creates a dynamic where formulators must continuously innovate to meet the diverging requirements of performance, safety, and cost-efficiency.
Geographic Distribution and Regional Dynamics
The geographic footprint of instant adhesive consumption reflects both established industrial bases and emerging growth corridors. North America represents a substantial revenue contributor, supported by mature manufacturing sectors, a strong electronics industry presence, and a healthcare market that demands advanced bonding solutions. Europe maintains a parallel position of significance, driven by its robust automotive and industrial manufacturing ecosystems, alongside increasing regulatory emphasis on environmental compliance that shapes product formulation strategies across the region.
Asia Pacific emerges as a particularly notable region in terms of market scale, reflecting the concentration of electronics manufacturing, rapid industrialization, and growing consumer markets across multiple economies. The region's expansive production capacity and increasing domestic consumption create a complex competitive environment where both multinational formulators and regional players vie for share. Latin America and the Middle East and Africa represent additional geographic dimensions, with growth potential tied to infrastructure development, industrial modernization initiatives, and gradually expanding manufacturing bases in select economies.
Regional dynamics are further complicated by divergent regulatory environments, varying raw material access, and differing labor cost structures that influence both product pricing and formulation priorities. Strategic market entry or expansion decisions require nuanced understanding of these regional characteristics rather than one-size-fits-all approaches. Companies that develop region-specific product portfolios and distribution strategies will find themselves better equipped to navigate the heterogeneous demands of global instant adhesive markets.
Competitive Landscape: Architects of Market Evolution
The instant adhesive market operates within a moderately concentrated competitive structure. Analysis of the competitive landscape reveals a market environment where the top three players command approximately 19.4 percent of total revenue, while the top five collectively account for roughly 22.5 percent. This concentration profile suggests a market that accommodates both established multinational corporations with extensive research and development capabilities and smaller, specialized formulators that compete through niche application expertise, regional distribution strength, or proprietary formulation technologies.
Among the prominent organizations shaping this landscape, Henkel AG and Co KGaA stands as a defining presence through its Loctite-branded instant adhesive and cyanoacrylate portfolio, which serves industrial, medical, and automotive applications with a reputation for performance reliability. The company's global distribution network and sustained investment in application-specific product development reinforce its position as a benchmark competitor. 3M Company maintains a parallel stature through its Scotch-Weld and Super-Fast instant adhesive lines, catering to electronics, industrial bonding, and medical use cases with a portfolio that emphasizes both performance and accessibility across diverse customer segments.
Huntsman Corporation contributes to the competitive ecosystem by supplying instant adhesive resins and solutions tailored for general industrial and construction bonding applications, leveraging its broader materials science expertise to support large-scale manufacturing customers. H.B. Fuller Company markets a diversified portfolio of instant adhesives designed for quick-bonding industrial and specialty applications, with recent strategic moves underscoring its commitment to capacity expansion and regional market servicing. Bostik SA, operating under the Arkema Group umbrella, develops and supplies instant engineering adhesives including the Born2Bond series, positioning its offerings for demanding environments that require robust performance under stress or temperature variation.
Toagosei Co Ltd brings specialized expertise in cyanoacrylate instant adhesives through its Aron Alpha brand, targeting industrial manufacturing markets with formulations optimized for production-line efficiency. Pidilite Industries Limited extends its reach across consumer, industrial, and craft bonding segments through the Fevikwik instant adhesive line, demonstrating the brand strength that can emerge from effective product positioning in both professional and retail channels. Permabond LLC, with its North American operations anchored from a UK base, specializes in high-performance instant adhesives designed for engineering and industrial use cases where bond reliability is paramount. Dymax Corporation rounds out the competitive array with its focus on UV and light-cure instant adhesives, particularly serving electronics and medical assembly applications where curing precision and speed are critical operational requirements.
Recent corporate developments highlight the strategic dynamism within this competitive field. In May 2026, H.B. Fuller Company executed significant capacity expansion initiatives, opening a new state-of-the-art facility in Cairo, Egypt, that adds manufacturing capacity for pressure-sensitive and non-pressure-sensitive adhesives serving over thirty market segments, including industrial adhesives. Concurrently, the company expanded its site in the United Arab Emirates to enhance manufacturing capabilities for waterproofing, woodworking, and industrial adhesives. These investments signal a deliberate strategy to strengthen regional manufacturing presence, reduce supply chain vulnerabilities, and position the company to capture growth in emerging markets with localized production capabilities.
The competitive dynamics extend beyond corporate strategy to encompass the broader forces that shape market access and product differentiation. Formulators must balance the imperative to innovate with the practical constraints of cost management and regulatory compliance, creating an environment where competitive advantage is increasingly derived from integrated solutions rather than commodity product offerings alone.
Raw Material Dynamics and Cost Structure Considerations
The economics of instant adhesive production are fundamentally shaped by raw material cost structures and supply chain volatility. Industry data indicates that raw material prices account for approximately 86 percent of the final instant adhesive product price, a proportion that makes feedstock cost management a central concern for profitability and pricing strategy. Monomer cost swings, in particular, exert significant influence on pack pricing, requiring manufacturers to maintain agile procurement strategies and, where feasible, hedging mechanisms to mitigate exposure to commodity price fluctuations.
During March 2026, stable but firm feedstock costs, particularly for methanol and acetone, contributed to steady firm pricing of cyanoacrylate in the USA market. This pricing environment reflects the interplay between raw material availability, production capacity utilization, and demand strength, creating conditions where margin preservation depends on operational efficiency and value-added product positioning rather than simple volume expansion. Companies that have invested in vertical integration, long-term supplier agreements, or alternative feedstock sourcing strategies are better insulated against the periodic cost pressures that characterize this segment of the materials market.
The sensitivity of final product pricing to raw material inputs also shapes competitive dynamics in meaningful ways. Larger, well-capitalized manufacturers may possess advantages in procurement scale and supply chain diversification, while smaller players may need to compete through service differentiation, specialized technical support, or regional market focus. Understanding these cost structure dynamics is essential for competitive analysis, pricing strategy development, and investment planning across the instant adhesive value chain.
Regulatory Pressures and Formulation Evolution
The instant adhesive industry operates within an increasingly complex regulatory environment that influences product formulation, market access, and compliance cost structures across multiple geographies. In the United States, Canada, and Australia, strict volatile organic compound regulations and occupational-health requirements compel formulators to develop low-VOC and low-odor instant adhesives, raising compliance costs while simultaneously creating opportunities for companies that can deliver compliant products without sacrificing performance. These regulatory pressures are not static; they evolve as governments and regulatory bodies refine their approaches to chemical safety, emissions control, and workplace health protection.
Across global markets, formulators are shifting toward low-VOC and REACH-compliant instant adhesives to meet tightening environmental standards. This shift represents more than a compliance exercise; it reflects a broader industry movement toward sustainable chemistry and environmentally responsible manufacturing practices that resonate with downstream customers and end consumers alike. Companies that proactively invest in compliant formulation development and maintain robust regulatory monitoring capabilities will find themselves with competitive advantages in markets where environmental compliance is increasingly a prerequisite for supply chain participation.
The medical sector introduces an additional regulatory dimension. New medical-grade cyanoacrylate formulations are being developed without CMR ingredients to comply with safety requirements for heat-resistant medical device applications. This formulation evolution addresses the stringent biocompatibility and safety standards that govern medical device manufacturing, creating specialized product opportunities for formulators with the technical expertise and regulatory documentation capabilities to serve this demanding segment. The intersection of regulatory compliance and product performance in medical applications underscores the value of specialized knowledge and the premium that sophisticated customers place on reliably compliant solutions.
These regulatory trends have strategic implications beyond product development. They influence market entry timing, geographic expansion feasibility, and the competitive positioning of companies with varying levels of regulatory infrastructure and expertise. Organizations that treat regulatory compliance as a strategic capability rather than a peripheral concern will be better equipped to navigate the evolving landscape and capitalize on the opportunities created by regulatory-driven product differentiation.
What This Report Delivers: Analytical Depth and Strategic Utility
This market research study is structured to provide executives, strategic planners, and industry analysts with a comprehensive yet actionable understanding of the instant adhesive market's current state and future trajectory. The report integrates macroeconomic market sizing and growth projections with detailed segmentation analysis, competitive intelligence, and an examination of the regulatory and raw material dynamics that shape market conditions. By situating quantitative data within a qualitative framework of industry forces, the study enables readers to move beyond surface-level market observations toward a nuanced grasp of the strategic factors that will drive performance over the forecast period.
The report's segmentation analysis provides visibility into how revenue distributes across product types, application verticals, and geographic regions, enabling readers to identify where demand concentration creates opportunities and where fragmentation requires targeted strategies. The competitive landscape assessment goes beyond company profiles to examine strategic positioning, recent corporate developments, and the structural characteristics of market concentration that influence competitive behavior and market access. The inclusion of raw material dynamics and regulatory trend analysis ensures that readers understand the cost and compliance environments that underpin product economics and market entry feasibility.
Importantly, this report is designed to support decision-making rather than merely describe market conditions. The analytical framework presented enables stakeholders to assess growth opportunities, evaluate competitive threats, plan capacity investments, and develop product strategies aligned with market realities. Readers seeking a comprehensive understanding of the instant adhesive market's opportunities and challenges will find the full report's detailed data sets, segmentation breakdowns, company profiles, and forward-looking analysis essential to formulating informed strategic responses.
Positioning for 2026 and the Decade Ahead
The instant adhesive market enters the 2026 to 2032 forecast period with a foundation of established growth, evolving competitive dynamics, and a regulatory and cost environment that demands strategic agility. The projected compound annual growth rate of 6.58 percent reflects sustained demand across multiple industrial sectors, but realizing the benefits of this growth requires more than passive market participation. Organizations must actively monitor raw material cost trajectories, adapt product portfolios to meet regulatory and performance requirements, and position themselves within the competitive landscape in ways that leverage their specific capabilities and market access advantages.
The companies that thrive in this environment will be those that treat market intelligence as a strategic asset, integrating deep understanding of segmentation trends, regional dynamics, raw material economics, and regulatory developments into coherent decision-making frameworks. Whether evaluating market entry opportunities, assessing competitive threats, planning capacity investments, or developing product innovation pipelines, access to comprehensive and timely market intelligence proves indispensable. This report is designed to provide exactly that foundation, offering the analytical rigor and strategic perspective needed to navigate the instant adhesive market with confidence through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Instant Adhesive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Golf GPS Market Valued at USD 215M in 2025, Projected to Grow at 6.98% CAGR Through 2032
By PW Consulting, 2026-09-07
The 2026 Golf GPS Market: Strategic Intelligence for Corporate Decision-Making
The global golf GPS and rangefinder sector stands at a inflection point. As course layouts become increasingly digitized, consumer expectations shift toward real-time analytics, and regulatory frameworks tighten around device certification, enterprises operating in this space must navigate a landscape defined by both opportunity and operational complexity. Our latest comprehensive market research on the Golf GPS Market delivers the analytical rigor required to transform uncertainty into actionable strategy for 2026 and beyond.
Shaving Pen Market
This report is not merely a retrospective on past sales figures or a generic projection of industry growth. It is a decision-grade intelligence asset designed for executive teams, product strategists, supply chain planners, and market entry analysts who require a clear line of sight into demand trajectories, competitive positioning, and structural market shifts. By synthesizing historical performance patterns, forward-looking demand signals, and granular product-category dynamics, the study constructs a multidimensional view of where value will be created, consolidated, or disrupted over the coming forecast horizon.
Online File-Sharing Platforms Market
Macro Trajectory and Structural Market Signals
Over the assessment window from 2020 through 2025, the global Golf GPS Market demonstrated consistent expansion, with revenue scales maturing across successive annual cycles. The trajectory reflects a market that has moved past early adoption volatility and entered a phase of stabilized growth driven by broader participation in golf, technological refinement in navigation hardware, and increasing integration of performance analytics into consumer devices. Looking ahead to the 2026-2032 forecast period, the research models a compound annual growth rate of 6.98%, anchored in baseline valuations established at the close of the historical review window. Revenue projections for the opening forecast year indicate continued upward momentum, with subsequent annual milestones reflecting an accelerating expansion curve as hardware ecosystems mature and software-enabled value propositions gain traction across diverse user segments.
Worldwide Proxy Server Reporting Software Market
The forecast architecture within the study isolates key inflection variables that will shape mid-decade performance. These include shifts in hardware form-factor preferences, the monetization pathways of companion applications, course-level data licensing models, and the pacing of professional versus recreational adoption cycles. By mapping these variables against regional demand intensity and competitive supply dynamics, the report enables stakeholders to anticipate revenue concentration patterns, evaluate the timing of category saturation, and calibrate investment horizons accordingly.
Importantly, the research treats market size not as a static endpoint but as a dynamic function of ecosystem readiness. High consumer spending environments have historically supported sustained expansion in golf technology categories, and the study isolates the demand-side conditions that will determine whether growth remains linear or accelerates through cross-category bundling, subscription-enabled analytics, and course-operator partnerships. The resulting analytical framework equips decision-makers with scenario-ready inputs rather than rigid single-point predictions.
Operational and Regulatory Dynamics Shaping the Competitive Field
The operating environment for golf GPS manufacturers and distributors has grown increasingly multifaceted. On the demand side, durable consumer spending capacity has underpinned category resilience through recent assessment years, allowing manufacturers to sustain launch cadences, expand accessory ecosystems, and invest in elevated data-capture capabilities without sacrificing margin stability. However, the supply and compliance pathway is undergoing structural adjustment. Recent regulatory developments require heightened attention from importers, assemblers, and channel partners. Beginning mid-2026, consumer product imports, including golf GPS devices, must electronically file certificates of compliance with U.S. Customs and Border Protection. This procedural shift introduces new administrative obligations that will affect lead times, customs clearance workflows, and cost structures for companies with cross-border supply chains.
Simultaneously, the regulatory footprint of established manufacturers continues to expand. Public registration data indicates that more than 1,200 GPS device models from a leading hardware manufacturer have been recorded for U.S. compliance, including specialized golf GPS configurations. This concentration of registered intellectual property and certified product variants underscores a broader industry reality: scale players are not only competing on feature sets and brand equity but also on the institutional capacity to navigate certification pipelines at volume. For smaller entrants and regional distributors, understanding compliance architecture is increasingly a strategic prerequisite rather than a back-office administrative task.
These dynamics interact with product strategy in meaningful ways. Manufacturers that integrate compliance readiness into early-stage design, localization, and channel planning will gain speed advantages in market entry and product refresh cycles. Conversely, organizations that treat regulatory filing as an afterthought may encounter friction in inventory turnover, regional rollout sequencing, and partnership negotiations with course operators who increasingly demand certified, auditable equipment for course management applications.
Research Architecture and Decision-Ready Content
The study is constructed to translate raw market intelligence into operational clarity. Readers will encounter a layered analytical structure that moves from overarching demand modeling to category-level differentiation, from regional intensity mapping to firm-level competitive positioning. Each section is designed to answer a specific strategic question that executives face when allocating capital, prioritizing product roadmaps, or evaluating partnership and distribution opportunities.
The report delivers detailed segmentation analysis across device categories, usage contexts, and geographic demand zones. Rather than presenting abstract totals, the research isolates the structural drivers behind each segment, including feature preferences, price-point elasticity, adoption barriers, and the role of accompanying software or analytics services. This approach allows readers to identify which sub-categories are experiencing incremental maturation, which are being reshaped by technological substitution, and where latent demand remains under-served by current product portfolios.
Competitive profiling is embedded within the analytical framework rather than appended as a standalone directory. The report examines how leading manufacturers position their offerings across precision distance measurement, on-course navigation, swing and shot analytics, and pace-of-play management. It evaluates product architecture choices, ecosystem lock-in strategies, content partnerships with course databases, and the extent to which brands leverage tradition, performance credibility, or digital convenience as differentiation levers.
Additionally, the study incorporates recent corporate activity to illustrate how strategy is being executed in near-real time. Product launches, display presentations at industry events, and brand campaign shifts are analyzed not as isolated news items but as indicators of strategic intent. By mapping these developments against broader category trends, the report helps readers distinguish between tactical promotions and genuine portfolio pivots.
Competitive Landscape: Positioning, Differentiation, and Strategic Signaling
The competitive field in golf GPS and related precision navigation hardware reflects a blend of established outdoor technology brands, specialized golf-performance companies, and regional specialists expanding their footprint through feature innovation and channel development. Several firms illustrate the dominant strategic archetypes shaping market evolution.
Garmin Ltd. continues to extend its footprint through integrated GPS ecosystems that span wearable devices, handheld units, and application-linked analytics. Recent product activity underscores a dual focus: advancing performance telemetry for engaged players while broadening accessibility for younger or entry-level users. The introduction of a touchscreen-enabled GPS handheld with expanded radar metrics and putting features signals investment in richer on-course data capture. At the same time, a junior-oriented GPS watch emphasizing skill-based tee positioning and pace management reflects a strategic interest in cultivating long-term user relationships and addressing slow-play concerns that affect course throughput and player experience.
Bushnell Corporation, operating through its golf division, maintains a strong association with precision distance measurement and performance compensation features. Its recent rangefinder introduction highlights continued emphasis on slope processing and display modernization, reinforcing the brand's positioning around accuracy, course management utility, and tournament-adjacent credibility. The firm's portfolio approach blends handheld optics, GPS-enabled wearables, and tracking devices, allowing it to address both traditional rangefinder buyers and users migrating toward multi-function performance tools.
Voice Caddie and Shot Scope Technologies exemplify the analytics-forward segment of the market, where hardware serves as a conduit for deeper performance insights. Voice Caddie's emphasis on OLED touchscreen interfaces and advanced swing analytics indicates a product philosophy that prioritizes on-device readability and post-round performance interpretation. Shot Scope Technologies has pursued a similarly data-centric direction, combining GPS hardware with app-linked performance tracking and AI-informed analytics. Its recent launch monitor collaboration and global brand campaign signal an effort to translate performance data into narrative-driven consumer engagement while expanding visibility in key demand regions.
Other participants reflect the breadth of specialization within the category. TecTecTec and Canmore Electronics focus on portable distance measurement and on-course navigation tools, serving users who prioritize compact form factors and straightforward distance feedback. iGolf Solutions contributes embedded GPS and Doppler-based solutions relevant to simulation environments and handheld applications, illustrating the convergence between on-course navigation and off-course practice technology. Precision Pro Golf's emphasis on audible guidance and speaker-integrated navigation highlights an alternative interaction model for players who prefer voice-assisted course management. Tagmarshal's cart-based GPS systems and pace-of-play software represent the course-operator side of the market, where device intelligence is leveraged to manage flow, scheduling, and operational efficiency rather than individual shot data alone.
Collectively, these profiles reveal a market in which differentiation is increasingly multidimensional. Hardware precision remains essential, but competitive advantage is now shaped by ecosystem integration, analytics usability, course database coverage, certification capacity, and the ability to address both recreational and operational stakeholder needs. The report's competitive analysis maps these dimensions systematically, enabling readers to evaluate where incumbents have structural advantages and where emerging players may find viable entry or disruption pathways.
Strategic Implications for 2026 Decision-Makers
For enterprises formulating 2026 strategies, the Golf GPS Market research provides several actionable implications. First, growth planning must account for the interaction between hardware refresh cycles and software-enabled value creation. Devices are no longer isolated purchase events; they are entry points into broader data, analytics, and course-commerce ecosystems. Companies that design roadmaps around companion services, subscription potential, and data interoperability will be better positioned to capture recurring value and extend product lifecycles.
Second, distribution and compliance strategy require proactive design. With evolving import-certification requirements and a heavily registered compliance landscape among scale players, market entrants and expanders must evaluate supply chain architectures for resilience, documentation readiness, and regional clearance efficiency. Organizations that integrate compliance planning into product localization and inventory sequencing will reduce operational friction and protect launch timing.
Third, competitive positioning should be evaluated through the lens of stakeholder coverage. The market now spans individual players seeking distance and performance insights, training-focused users seeking swing and strategy improvement, tournament-adjacent environments demanding precision and reliability, and course operators seeking flow management and operational visibility. Firms that align product features, communication narratives, and channel partnerships with the specific priorities of each stakeholder group will differentiate more effectively than those competing solely on generic navigation functionality.
Fourth, regional demand intensity and segment maturity patterns should inform market entry sequencing. The research isolates where demand is concentrated, where adoption curves are steepening, and where product-category preferences indicate preference for handheld devices, wearables, or application-based solutions. These insights help strategists prioritize geographic rollout, tailor product-mix decisions, and allocate marketing investment toward the most receptive demand environments.
Finally, the study supports risk-aware scenario planning. By connecting historical demand behavior, forecast trajectory, competitive concentration, and regulatory shifts, it provides decision-makers with a structured basis for stress-testing assumptions about pricing, channel access, product substitution, and compliance cost exposure. This is particularly valuable in a market where major players hold substantial concentration, making new entry or portfolio expansion dependent on clear strategic differentiation and operational preparedness.
Why This Research Is Built for Action
The report is intended to serve as a working reference for strategy formulation, not merely a one-time read. It combines macro market modeling with segment-level interpretation, competitive profiling with recent corporate event analysis, and regulatory context with supply-chain relevance. By maintaining a consistent focus on decision applicability, the study ensures that every analytical component ties back to a practical strategic question.
Readers will find structured coverage of market size evolution, forecast progression, segmentation behavior across device types, usage contexts, and regional demand, as well as detailed profiles of key companies and their strategic offerings. The integration of recent product launches, campaign activity, and compliance dynamics enables a near-term view of how competitive momentum is being generated and where operational friction may emerge.
Access the Complete Intelligence Package
The narrative above previews the analytical orientation and strategic relevance of the full study. To support precise planning, the complete research provides the underlying segmentation detail, competitive benchmarking, regional demand patterns, and forecast structures necessary for rigorous decision-making. These components are designed to be referenced during product planning cycles, market entry evaluations, partnership assessments, and capital allocation reviews.
For executive teams seeking a comprehensive, decision-grade view of the Golf GPS Market through 2026 and across the extended forecast horizon, the full report delivers the depth, structure, and strategic context required to move from observation to action.
Discover the complete market research and access detailed segmentation, competitive analysis, and forecast intelligence tailored for strategic planning.
For detailed analysis of this topic, please visit the official page: Golf GPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wireless Antenna Market Hits $5.5B in 2025, Projects 5.3% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Radio Frequency Foundations: Navigating the Wireless Antenna Market in 2026
The wireless connectivity landscape is entering a decisive phase. As enterprises across telecommunications, automotive, infrastructure, and industrial IoT scale their next-generation deployments, the antenna system has evolved from a passive peripheral to a critical strategic asset. The performance envelope of every network now hinges on antenna architecture, RF integration, and the ability to localize production while navigating volatile raw material economics. For leadership teams making capital allocation, vendor selection, and roadmap decisions in 2026, a rigorous, data-anchored view of the wireless antenna market is no longer optional—it is a prerequisite for defensible execution.
Content Management Tool Market
The market research published by PW Consulting maps this ecosystem with a longitudinal lens, tracing historical performance from 2020 through 2025 and projecting trajectory dynamics across the 2026 to 2032 forecast horizon. The narrative that emerges is one of steady structural expansion under intensifying technical and supply chain complexity. Total market revenue has demonstrated consistent year-over-year progression, moving from approximately 4.25 billion USD in 2020 to a 2025 base of 5.5 billion USD. The forward outlook points to continued scale with a projected 2026 valuation near 5.95 billion USD, followed by a measured climb toward 7.9 billion USD by 2032. This growth arc corresponds to a compound annual growth rate of approximately 5.3 percent across the full forecast window—indicating resilient demand that is neither speculative nor fragile, but rather rooted in multi-sector infrastructure build-out.
Worldwide Agricole Joystick Handle Market
Yet top-line trajectory is only the surface layer of strategic relevance. The real differentiation for enterprise decision-makers lies in understanding where value concentrates, which technology archetypes command premium positioning, and how regulatory shifts and commodity exposure will reshape cost structures. The following analysis previews the analytical dimensions of our full market research, illustrating how the study is engineered to convert market complexity into executable intelligence. The granular regional shares, segment-specific dollar allocations, and sub-segment performance splits are preserved within the complete dataset. This article serves as a strategic orientation—demonstrating methodology, competitive context, and decision-use cases—while directing readers to the full report for the precise figures required for board-level modeling and procurement planning.
Worldwide Industrial Pneumatic Brake Market
From Macro Trajectory to Strategic Signal
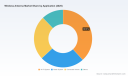
A market expanding at this cadence does not reward reactive purchasing or generic vendor evaluation. The wireless antenna space is shaped by overlapping demand vectors: continued densification of mobile networks, the proliferation of high-throughput Wi-Fi environments, the data collection requirements of radar and sensing architectures, and the antenna-intensive design of connected vehicle platforms. Each vector imposes distinct performance tolerances, form-factor constraints, and reliability expectations. Understanding how these application domains interact with evolving antenna types—MIMO, MISO, SIMO, and other specialized configurations—requires an analytical framework that ties architectural capability to market share dynamics without oversimplifying the trade-offs.
Our research is structured to make that connection actionable. Rather than presenting market size as an isolated number, the analysis develops a multi-dimensional segmentation that reveals how demand patterns diverge across technology classes, deployment environments, and geographic operating conditions. This approach allows strategists to identify where growth is genuinely structural versus where it reflects temporary project cycles. It also clarifies how concentration dynamics shape negotiation leverage, supplier risk, and long-term pricing behavior. With the top five firms collectively accounting for roughly 46 percent of market revenue and the top three approaching 42 percent, the competitive environment exhibits meaningful consolidation alongside a persistent tail of specialized innovators. That duality—concentrated scale players alongside targeted niche capabilities—defines the sourcing strategy challenge that many procurement and engineering leaders face in 2026.
What the Research Delivers: Practical Intelligence for Execution
The full market research is designed as a working instrument rather than a static snapshot. Beyond foundational sizing and trajectory modeling, the study integrates qualitative and quantitative layers that directly support planning across R&D, procurement, sales strategy, and risk management. The analytical content is organized to answer the operational questions that executives routinely raise when evaluating antenna-intensive programs:
- Technology architecture comparisons that clarify how different antenna configurations align with coverage, capacity, and integration requirements across 5G, Wi-Fi, radar, and connected mobility environments.
- Application-level demand mapping that traces how Wi-Fi systems, radar platforms, connected vehicle architectures, and adjacent use cases are influencing volume mix, specification expectations, and procurement timelines.
- Competitive profiling that moves beyond press-release narratives to examine product orientation, solution breadth, and strategic emphasis across leading incumbents and specialized suppliers.
- Recent corporate developments that illustrate how major players are adjusting manufacturing footprints, product portfolios, and partnership strategies in response to regional market pressures and infrastructure priorities.
- Macro and input-cost context that connects material exposure, regulatory actions, and commodity trends to realistic cost-structure scenarios for antenna and RF component programs.
This integrated design matters because antenna strategy is rarely a single-variable decision. Choosing a supplier, selecting an antenna type, or committing to a localization plan typically requires simultaneous consideration of performance specs, supply continuity, compliance exposure, and total cost of ownership. By combining market sizing with company-level development tracking and input-market monitoring, the research provides a basis for scenario planning rather than point forecasting. Decision-makers can pressure-test assumptions about lead times, pricing stability, and technology roadmaps against a common evidence base, reducing reliance on fragmented intelligence or supplier-derived narratives.
Competitive Dynamics: Scale Incumbents and Specialized Innovators
The competitive landscape in wireless antenna systems is characterized by companies that compete at different layers of the value chain. Several established network infrastructure leaders anchor the market through high-performing mobile network portfolios, passive antenna production, and RAN-integrated antenna solutions. These players continue to emphasize network-level performance, ecosystem coordination, and the ability to support large-scale operator deployments. At the same time, a parallel track of firms focuses on digital antenna advancement, intelligent optimization, and emerging optical or meta-structure approaches that anticipate next-generation base station requirements. The strategic implication is clear: antenna procurement and partnership decisions increasingly involve trade-offs between proven scale, integration depth, and technology optionality.
In addition to the large infrastructure-oriented players, the market includes specialists whose relevance is defined by product focus rather than total portfolio breadth. High-gain multi-protocol antenna and distributed antenna system providers serve deployment environments where densification and multi-standard compatibility are paramount. RF semiconductor and antenna module suppliers contribute at the component and integration level, where size, efficiency, and RF performance directly shape end-device and infrastructure design. Others concentrate on connectivity-intensive venues, stadium-grade infrastructure, and DAS-oriented architectures, while a distinct set of organizations targets IoT, cellular modules, and broadband measurement systems. This pluralistic structure means that the optimal sourcing approach often depends on deployment context, and a single supplier relationship rarely satisfies every requirement.
Recent activity from core participants illustrates how strategy is being translated into operational moves. One major antenna systems producer has expanded local manufacturing in India through collaboration with electronics manufacturing partners, advancing toward full localization of passive antenna production by mid-2025 and bringing export-ready antennas into the market shortly thereafter. In parallel, another large technology provider has publicly showcased commercial achievements in digital antenna technology, emphasizing intelligent transformation for base station environments. Alongside these infrastructure-scale moves, specialized suppliers have secured multi-year programs tied to advanced Wi-Fi deployments and launched new high-gain antenna lines optimized for contemporary 5G and Wi-Fi environments. These developments are not isolated press items; they are indicators of where manufacturing proximity, product modernization, and application-specific engineering are being prioritized.
Our report surfaces these patterns in a structured competitive format, allowing readers to assess not only who the key players are, but how their recent actions signal shifts in capability, geographic emphasis, and product direction. Full company profiles, link references, and event-level tracking are available in the complete version of the study, supporting detailed vendor benchmarking and strategic fit analysis.
The 2026 Decision Environment: Materials, Regulation, and Resilience
Strategic planning for antenna-intensive programs in 2026 must account for input-market volatility and regulatory dynamics as first-order factors, not peripheral concerns. The materials ecosystem feeding RF and antenna manufacturing has shown significant price movement and geopolitical sensitivity. Copper, a core conductor and structural input across many antenna and RF designs, experienced notable price levels in 2025 with forward expectations pointing toward materially higher annual averages in 2026. At the same time, precious metal exposure continues to fluctuate, with palladium and gold prices reflecting recovery patterns and high-volatility trading ranges that influence component cost models, plating requirements, and broader electronics pricing sentiment.
These commodity trends become strategically meaningful when combined with regulatory actions affecting material availability. Export controls on selected rare earth elements and magnets introduced in 2025 have created additional licensing requirements and supply chain friction. Analysts expect these controls to contribute to production delays and cost pressure across semiconductor and RF antenna domains in 2026. For organizations dependent on specialized magnetics, rare-earth-informed components, or imported intermediate materials, the implication is not simply a pricing challenge but a planning challenge: lead-time assumptions, qualification cycles, and inventory strategies need to be re-evaluated in light of constrained and conditional supply.
This is precisely the context in which a structured market study adds value. The PW Consulting research incorporates macro and input-market indicators that help leadership distinguish between temporary fluctuation and structural cost shifts. By aligning market trajectory with material exposure and regulatory risk, the study enables more credible scenario analysis. Procurement teams can better anticipate where cost escalation is likely to persist; engineering leaders can weigh material-critical design choices with greater confidence; and executive teams can assess whether strategic options such as supplier diversification, design standardization, or regional sourcing are justified by the market environment rather than by speculation.
Using the Study to Strengthen 2026 Decisions
The practical value of this market research lies in how it connects external market conditions to internal decision processes. For telecom and infrastructure organizations, the study supports roadmap alignment between antenna capability selection and network transformation priorities, including Open RAN considerations, multi-protocol deployment needs, and densification strategies. For automotive and connected-vehicle stakeholders, it clarifies how antenna demand is integrating into mobility platforms and what product orientations are gaining commercial traction. For enterprises building out Wi-Fi and venue-grade connectivity, it highlights the relevance of high-gain and distributed antenna approaches while mapping recent contract and product activity in that segment. For industrial and IoT-focused teams, the study creates visibility into module-integrated antenna solutions and RF front-end trends that influence device form factors and performance targets.
Because the detailed segmentation data—regional shares, application splits, and technology-class allocations—are maintained in the full report, readers can use the complete dataset to build forecasts, budget models, and sourcing comparisons that reflect their specific operating context. The preview provided here intentionally preserves strategic direction while reserving the exact numerical breakdowns for the full publication. That design reflects a core principle of high-value market intelligence: the public-facing narrative demonstrates analytical credibility and relevance, while the precise figures that support competitive benchmarking and financial planning are delivered in the structured research product.
For organizations making antenna-related decisions in 2026, the strategic imperative is to move from general awareness to quantified readiness. That means understanding not just that the market is expanding, but where growth is concentrated, how competitive dynamics affect supplier leverage, and which external factors are most likely to alter cost and availability assumptions over the forecast period. It also means grounding those judgments in a consistent methodology that can be revisited as conditions change.
Closing Perspective
The wireless antenna market in 2026 presents a distinctive combination of steady growth, technological differentiation, and supply-side complexity. Demand is being sustained by broad infrastructure and connectivity imperatives, while competitive behavior and input-market conditions are reshaping the economics of participation. In this environment, effective strategy depends on intelligence that is both wide in scope and precise in execution. The full PW Consulting Wireless Antenna Market Research provides that foundation, offering executives a structured view of market size, segmentation dynamics, competitive moves, and material/regulatory risk factors that influence planning across the 2026 to 2032 horizon.
The complete edition includes the granular regional and application splits, technology-class allocations, and detailed company profiles required for rigorous benchmarking and financial modeling. We invite decision-makers, procurement leaders, and strategy teams to access the full report to retrieve the specific figures and structured datasets needed for board-ready analysis and actionable planning. In a market defined by both opportunity and volatility, depth of intelligence is the differentiator between reactive adaptation and disciplined strategic advantage.
For detailed analysis of this topic, please visit the official page: Wireless Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Contact Center Market Reaches $47.18B in 2025 with 11.05% CAGR Thru 2032
By PW Consulting, 2026-09-07
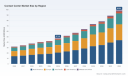
The Contact Center Market in 2026: Why Strategic Intelligence Is No Longer Optional
The contact center has evolved from a cost-bearing operational unit into a strategic revenue and retention engine. Over the past five years, that transformation has accelerated, driven by shifting customer expectations, the rapid infusion of artificial intelligence into customer experience workflows, and a market that has consistently outpaced broader enterprise technology growth. As organizations finalize their 2026 investment decisions, the difference between reactive procurement and proactive competitive positioning will come down to one factor: the quality of the intelligence guiding those choices.
Electric Mosquito Repellent Incense Market
This article serves as a strategic preview of PW Consulting’s latest Contact Center Market research. It highlights the structural forces reshaping the industry, the competitive dynamics that will define vendor selection, and the operational variables that will determine whether contact center investments deliver measurable returns. The full report contains the granular segmentation, regional contributions, application-level breakdowns, and company-specific benchmarking data required to translate these macro trends into precise budget allocations and roadmap decisions.
Single Bolt Cable Cleat Market
The Market Trajectory: Sustained Growth Meets Structural Pressure
The contact center market has demonstrated consistent expansion across the historical window and is positioned for continued growth through the forecast period. Total market revenue climbed from approximately $32.0 billion at the start of the historical baseline to $47.2 billion by the base year, with the trajectory carrying forward into the early forecast years before reaching nearly $99.0 billion by the end of the projection window. The implied compound annual growth rate across the forecast horizon stands at 11.05%, a pace that signals more than incremental adoption; it reflects a fundamental restructuring of how enterprises deploy, scale, and monetize customer engagement infrastructure.
Planar ITO Target Market
That growth is not uniform across all vectors. The market is being pulled forward by digital channel adoption, AI-infused routing and automation, and the migration of legacy voice-heavy environments toward cloud-native architectures. At the same time, pricing dynamics, labor economics, and regulatory or licensing shifts are introducing new pressure points that require disciplined analysis. Enterprise decision-makers cannot rely on top-line growth figures alone. They need to understand where value is being created, where margins are being compressed, and which vendor capabilities will matter most as the ecosystem matures.
Our research unpacks these layers without oversimplifying them. Rather than presenting a single aggregated number and calling it strategy, the report maps the growth path against the operational realities that will shape budgeting, vendor negotiations, and internal capability building through the forecast period.
What the Research Delivers: An Operational Blueprint, Not Just a Forecast
A market study earns its place in the C-suite only when it connects numbers to decisions. This report is structured to do exactly that. It combines historical grounding, forward-looking projections, and actionable operational context so that strategy, procurement, and customer experience leadership can align around a shared set of assumptions.
The core content is designed around practical use cases:
- Market sizing and trajectory analysis that anchors planning in a defensible historical baseline and extends it through the full forecast window, giving leadership a coherent view of growth momentum rather than isolated snapshots.
- Segment-level intelligence covering regional footprints, engagement types, and application categories so teams can assess where demand is concentrating and how deployment priorities are shifting across customer-facing and internal operations.
- Competitive landscape profiling that examines the strategic positioning, platform capabilities, and market focus of major vendors, enabling more informed shortlisting, negotiation, and partnership decisions.
- Industry context and disruption signals that translate operational pressures, pricing shifts, and technology-driven cost dynamics into implications for staffing models, workflow design, and total cost of ownership.
- Strategic implications and decision frameworks that help organizations translate market intelligence into procurement timing, vendor evaluation criteria, and internal investment priorities.
Throughout the report, the emphasis is on usability. The goal is not to overwhelm readers with data, but to give them a structured way to ask better questions: Which channels are gaining priority in the next planning cycle? Which vendor strengths map to our industry requirements? How should we evaluate AI-enabled automation against labor cost exposure? Where do concentration risks or pricing shifts alter the value equation?
The Competitive Landscape: Ten Vendors, Distinct Plays, Shared Direction
The contact center market is neither a commodity arena nor a monolithic platform race. It is a competitive field where vendors differentiate through architecture, vertical specialization, AI integration depth, and workforce optimization tooling. The research profiles a broad set of leading players, each pursuing a distinct interpretation of what the modern contact center should deliver.
Five9 positions its offering around a cloud-native Intelligent CX platform built for enterprise scale, emphasizing AI-powered agent assist, predictive routing, and omnichannel orchestration. Genesys leans into its Genesys Cloud CX environment, combining journey orchestration, AI chatbots, and workforce engagement tools within a unified omnichannel framework. NICE contributes the CXone platform, with embedded AI focused on workforce optimization, quality management, and customer journey automation. Talkdesk differentiates through its CX Cloud and industry-specific AI experience clouds designed for vertical contact center solutions.
Dialpad takes an AI-first stance, centering on real-time transcriptions, agent flexibility, and outbound calling capabilities. Verint emphasizes AI-powered workforce management and quality management integrated into contact center operations, appealing to organizations that want tighter control over performance and compliance. Nextiva offers all-in-one unified communications and contact center solutions, pairing AI-driven support with transparent per-user pricing. RingCentral brings omnichannel capabilities and AI-powered customer interactions through its RingCentral Contact Center and RingCX offerings. Vonage targets enterprise clients with custom contact center solutions that blend AI agents and omnichannel integration. Zoom rounds out the field with Zoom Contact Center, focused on AI-first total experience capabilities for unified voice and collaboration.
What matters strategically is not simply that these vendors exist, but how their differentiating bets map to organizational needs. A company prioritizing vertical-specific AI workflows will evaluate the market differently from one optimizing for workforce management granularity or omnichannel journey orchestration. The report examines these positioning strategies in detail, giving procurement and IT leaders a sharper lens for vendor evaluation rather than a generic leaderboard.
The competitive context is also being reshaped by external capital and product momentum. Recent funding activity underscores how aggressively investors are backing AI-native support automation and messaging-centric customer support platforms. In August 2025, Capacity announced $92 million in new investments, bringing total funding to more than $155 million for its AI-powered support automation platform. Around the same time, Pylon secured $31 million in Series B funding for a B2B customer support platform built specifically for business messaging environments. These moves signal a market that continues to attract capital where automation, messaging, and AI-driven support intersect, reinforcing the importance of evaluating not just established incumbents but also fast-moving entrants that may alter service models and pricing expectations.
Market Dynamics at a Glance: Cost, Pricing, Licensing, and the AI Leverage Point
Behind the headline growth figures lies a set of operational dynamics that will directly affect 2026 planning. The most consequential is the economic leverage created by AI-driven automation. Conversational agents and AI-supported workflows are reducing contact center agent labor costs at scale, with sector analysis pointing to a global reduction potential reaching up to $80 billion. That figure is not abstract. It reflects a structural shift in how organizations think about Tier 1 handling, escalation design, and agent utilization. When a single inbound call to a live agent can cost between $6 and $15 while AI can manage comparable Tier 1 queries for roughly $0.30 to $0.50 per interaction, the value case for intelligent automation becomes a central component of contact center strategy rather than a peripheral efficiency project.
At the same time, cost advantages are being offset in part by pricing pressure and licensing shifts across enterprise software portfolios. Vendors across the contact center space have implemented aggressive price increases across portfolios effective in mid-2026. Microsoft’s ecosystem changes introduce additional complexity: Microsoft 365 frontline worker licenses tied to contact center use are rising between 25% and 33% starting in July 2026, while Microsoft business tiers used in contact center workflows are increasing between 12% and 17% over the same window. These changes matter because many organizations run hybrid stacks in which contact center functionality intersects with collaboration, identity, desktop, and productivity tools. Licensing exposure is no longer a back-office detail; it is a variable that can materially alter total cost of ownership.
The strategic implication is clear. Growth in the market does not guarantee easier economics for every buyer. Organizations that evaluate contact center investment through a single lens—platform features or headline price—risk underestimating the combined impact of automation savings, vendor pricing, licensing escalation, and workflow redesign. The research integrates these dynamics so leaders can model scenarios with more realism and avoid decisions built on incomplete cost assumptions.
Why This Research Matters for 2026 Decision-Making
2026 is shaping up to be a year in which contact center strategy is tested on multiple fronts at once. Customer experience expectations continue to rise, AI capabilities are maturing faster than many internal operating models can absorb, and vendor pricing and licensing structures are becoming more complex. In that environment, decision quality depends on clarity. Leaders need to know not just that the market is expanding, but how growth is distributed across channels, applications, and regions; not just which vendors are prominent, but which capabilities align with specific operational priorities; and not just that AI is reshaping labor economics, but how automation savings interact with licensing and vendor pricing.
The full report is designed to answer those questions with enough specificity to support budgeting, sourcing, and roadmap planning. It builds on a historical perspective from 2020 through the base year, extends into the forecast window through the end of the decade and beyond, and frames the discussion around the segmentation splits, competitive profiles, and industry context that matter most to enterprise buyers. Where broad market numbers establish trust, the deeper segmentation and company-level detail provide the leverage needed to make precise commitments.
This preview is intentionally high-level. It establishes the strategic stakes and the analytical rigor behind the study, but it does not reveal the full segmentation values, regional contributions, application-level breakdowns, or detailed company benchmarking that constitute the core intelligence of the report. Those elements are where the difference between a generic market narrative and an actionable decision framework is made. They are also where procurement teams, customer experience leaders, and finance stakeholders will find the comparisons and scenario inputs needed to justify investment choices with confidence.
How to Use This Intelligence
The most valuable contact center research is not the one that simply identifies trends. It is the one that helps teams convert trends into decisions. PW Consulting’s report is structured to support that conversion across several practical pathways:
- Strategic planning: Align long-range customer engagement investment with market growth direction and segmentation signals rather than legacy assumptions.
- Vendor evaluation: Compare platform positioning, AI integration depth, and workforce optimization strengths against actual operational requirements instead of generic feature lists.
- Cost modeling: Incorporate automation economics, vendor pricing trajectories, and licensing escalation into total cost of ownership analysis for more credible financial planning.
- Operating model design: Use channel and application context to inform staffing, workflow, escalation, and automation balance across inbound and outbound interactions.
- Risk management: Monitor market concentration, pricing momentum, and fast-moving entrants so that sourcing decisions reflect not only current capabilities but also future ecosystem shifts.
Each of these pathways depends on access to the underlying segmentation and benchmarking detail that the report provides. The macro trajectory gives the market its shape, but the segmentation and company-level analysis give leaders the resolution they need to act.
A Preview With Purpose
The contact center market in 2026 is defined by momentum, complexity, and opportunity. Revenue expansion measured in the tens of billions, an 11.05% forecast compound annual growth rate, and a competitive field of sophisticated platform vendors all point to a sector in transition. Yet the real strategic challenge is not recognizing that the market is growing. It is understanding how that growth breaks down across regions, engagement types, applications, and vendor plays, and how cost dynamics—from labor savings to licensing increases—alter the value equation for each organization.
This article has outlined the structural forces, competitive context, industry dynamics, and decision implications that make the Contact Center Market research relevant to 2026 planning. What it has not done is expose the full segmentation data, company-specific benchmarks, and granular comparisons that sit at the heart of the report. That detail is reserved for the complete study, where it can be used with the precision it requires.
For executives, procurement leaders, and customer experience strategists preparing for the year ahead, the opportunity is to move from high-level awareness to grounded intelligence. The full report delivers that next layer: the segmented view, the competitive comparisons, and the operational context needed to make contact center investment a source of competitive advantage rather than a reactive cost line.
For detailed analysis of this topic, please visit the official page: Contact Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stable Isotope Analyzer Market to Reach $174M by 2032, Growing at 8.7% CAGR
By PW Consulting, 2026-09-07
Decoding the Future of Precision: Strategic Intelligence for the Stable Isotope Analyzer Market Through 2032
In the landscape of modern analytical science, the ability to measure atomic variance with extreme precision is not merely a technical capability—it is a strategic imperative. From verifying the geographical origin of premium food products to tracking carbon cycles in environmental research and ensuring the integrity of pharmaceutical compounds, stable isotope analyzers have become the bedrock of empirical truth in high-stakes industries. As we navigate the post-2025 economic environment, organizations relying on these technologies face a dual challenge: maintaining analytical rigor while navigating a rapidly consolidating vendor landscape and evolving regulatory frameworks.
Shaving Pen Market
PW Consulting is pleased to introduce our comprehensive market intelligence study on the Stable Isotope Analyzer Market. This report is not simply a collection of statistics; it is a decision-support tool designed for C-suite executives, R&D directors, and investment strategists who need to understand where the market is heading between 2026 and 2032. Below, we outline the strategic contours of this industry, highlighting the growth trajectories, competitive tensions, and regulatory shifts that will define the next decade of analytical instrumentation.
Vessel Towing Pins Market
Market Trajectory: Sustained Growth Amidst Technical Maturation
The stable isotope analysis sector has demonstrated remarkable resilience and consistent expansion over the past half-decade. Following a historical evaluation period from 2020 to 2025, the market has established a robust foundation for the forecast period extending through 2032. Our analysis indicates that the global market revenue, measured in USD millions, has climbed from 71.0 million in 2020 to an estimated 98.0 million in 2025. This historical progression sets the stage for an accelerating trajectory in the coming years.
Worldwide 1,3-Di-4-Pyridylpropane Market
For strategic planners, the most critical figure in this landscape is the projected Compound Annual Growth Rate (CAGR) of 8.7 percent during the forecast horizon. This growth rate suggests that the market will expand from approximately 103.76 million in 2026 to 174.0 million by 2032. Such sustained expansion implies more than just incremental adoption; it signals a structural integration of isotope analysis into broader industrial and scientific workflows. Organizations that position themselves correctly during this growth phase stand to capture significant value, while those that lag risk obsolescence in an increasingly precision-driven economy.
It is important to note that this growth is not uniform across all vectors. The market is being shaped by specific technological preferences and application-driven demands that vary significantly by sector. Understanding these underlying currents is essential for accurate capacity planning and investment allocation. Our report delves deep into these nuances, providing a granular view of how different technology types and application verticals are contributing to the overall revenue pool without exposing the specific segmentation percentages that constitute our proprietary intelligence.
Technological Architectures: The IRMS and Laser Dichotomy
At the hardware level, the market is primarily defined by two competing technological architectures: Stable Isotope Ratio Mass Spectrometry (IRMS) and Laser-based systems. The IRMS segment, particularly continuous-flow and dual-inlet configurations, continues to dominate the installed base due to its versatility and established track record in high-precision measurements. Major manufacturers in this space have integrated these spectrometers with elemental analyzers to create seamless workflows for solid, liquid, and gaseous samples.
Conversely, laser-based technologies are carving out a significant niche, driven by advantages in speed, portability, and specific sensitivity profiles that mass spectrometry sometimes cannot match in field conditions. The interplay between these two technology streams creates a complex procurement environment. Buyers must weigh the gold-standard precision of traditional IRMS against the operational efficiencies and emerging capabilities of laser spectroscopy.
Our research provides a detailed comparison of these technological paths, analyzing how recent product announcements are shifting the balance. For instance, recent developments in benchtop combined systems are blurring the lines between laboratory-bound precision and operational ease. Understanding which technology aligns with specific organizational goals—whether it be high-throughput screening or ultra-high precision ratio measurement—is a key deliverable of this report. We examine the implications of these technological choices on total cost of ownership, maintenance overhead, and future-proofing against regulatory changes.
Application Verticals: Drivers of Demand Across Sectors
Demand for stable isotope analyzers is propelled by a diverse set of application verticals, each with unique growth drivers and compliance requirements. Environmental sciences remain a primary catalyst, fueled by the global imperative to monitor climate change, track pollution sources, and understand ecological cycles. The need for precise isotopic fingerprinting in water resources, soil health, and atmospheric studies ensures a steady baseline demand for high-performance instrumentation.
In the food and beverage industry, the focus has shifted sharply toward authenticity and safety. As supply chains become more globalized and complex, the risk of adulteration increases. Stable isotope analysis serves as a definitive tool for verifying origin claims, detecting fraud, and ensuring compliance with labeling standards. This application area is particularly sensitive to regulatory shifts, making it a volatile but high-potential segment for instrument manufacturers and service providers.
Medical and pharmaceutical applications represent another critical growth engine. In drug development, stable isotopes are used in metabolic studies, ADME (Absorption, Distribution, Metabolism, and Excretion) profiling, and as internal standards for mass spectrometry-based assays. The medical sector demands instruments that operate within strict regulatory environments, including GLP-compliant and CLIA-certified laboratory settings with systems validated under 21 CFR Part 11 for FDA and EMA accepted data. The intersection of analytical hardware and clinical compliance creates a specialized sub-market with distinct procurement cycles and validation hurdles.
Industrial applications, ranging from petrochemical analysis to material science, complete the demand picture. Here, the focus is often on process optimization and quality control. By understanding the relative weight and growth potential of these verticals, stakeholders can tailor their market entry strategies or expansion plans. Our report maps these application landscapes to specific regional and technological trends, offering a holistic view of where value is being created.
Competitive Landscape: Consolidation and Innovation
The vendor ecosystem for stable isotope analyzers is characterized by a moderate to high level of concentration, with a handful of key players commanding a significant share of the market. Our analysis highlights a competitive environment where established giants leverage extensive portfolios and service networks, while specialized innovators drive technological breakthroughs.
Thermo Fisher Scientific Inc., headquartered in Waltham, Massachusetts, remains a pivotal force in the market. Their DELTA series of continuous-flow and dual-inlet isotope ratio mass spectrometers, integrated with elemental analyzers, sets a benchmark for performance and reliability. Their ability to provide end-to-end solutions from sample preparation to data analysis creates high switching costs for customers, reinforcing their market position.
Elementar Analysensysteme GmbH, based in Langenselbold, Germany, is another cornerstone of the industry. Their IsoPrime and EA-IRMS systems are renowned for high-performance analysis across various sample types. Notably, Elementar has been proactive in aligning its products with emerging regulatory standards. In March 2025, the company announced that its EA-IRMS products were compliant with the new European CEN-18054 method for food authenticity testing. This move underscores the importance of regulatory alignment as a competitive differentiator in regions with strict food safety laws.
Sercon Ltd., operating from Crewe, United Kingdom, has made significant strides in system integration. In June 2025, Sercon announced the world's only benchtop combined EA-IRMS system with enhanced integration for stable isotope analysis. This development addresses a growing market desire for compact, user-friendly systems that do not sacrifice analytical power. Such innovations are critical for expanding the user base beyond large centralized laboratories to smaller facilities or field-deployable units.
Other notable participants include Isotopx Ltd. and Nu Instruments Ltd., both based in the United Kingdom. Isotopx produces the SIRIX gas source IRMS instruments optimized for high-precision stable isotope ratio mass spectrometry, catering to users who require exceptional accuracy. Nu Instruments offers high-precision continuous-flow IRMS systems, further strengthening the UK's position as a hub for analytical instrument innovation.
Cambridge Isotope Laboratories, Inc., located in Tewksbury, Massachusetts, plays a unique role in the ecosystem. While they are a key company in the broader market context, their primary contribution lies in providing the stable isotope-labeled compound standards and reference materials required for calibration and use in analyzer systems. Without these critical consumables, the hardware cannot function accurately. In October 2025, Cambridge Isotope Laboratories launched ISOAPI-D™, a unified brand of deuterated intermediates for API synthesis. This product launch highlights the interconnectedness of the instrument market with the consumables and reagents sector, suggesting that vertical integration or strategic partnerships between instrument makers and reagent suppliers could be a future trend.
The market concentration metrics indicate that a significant portion of revenue is controlled by the top players, creating barriers to entry for new competitors. However, the pace of innovation suggests that disruptive technologies or niche applications could still open avenues for specialized players. Our report analyzes the strategic moves of these key companies, evaluating their product pipelines, geographic footprints, and partnership strategies to forecast potential market shifts.
Regulatory and Industry Dynamics: The Compliance Imperative
One of the most significant factors influencing market dynamics in the 2026-2032 period is the evolving regulatory landscape. Compliance is no longer a backend concern; it is a primary driver of technology adoption and investment. The introduction of standards such as CEN-18054:2024, which establishes clear guidelines for the analysis of food samples using EA-IRMS, directly impacts instrument selection. Laboratories must ensure their hardware and workflows can demonstrate compliance with such standards to operate in regulated markets.
In the medical and pharmaceutical sectors, the stakes are even higher. Analyses performed in GLP-compliant, CLIA-certified laboratory environments require systems that are validated under 21 CFR Part 11. This ensures that data is accepted by regulatory bodies like the FDA and EMA. Manufacturers who can provide instruments with built-in compliance features or seamless integration with validated workflows hold a distinct advantage. The requirement for data integrity and traceability is pushing the industry toward more automated, secure, and auditable systems.
Furthermore, regulatory bodies are increasingly focusing on real-time data and clinical trial efficiency. For example, recent announcements from the FDA regarding major steps to implement real-time clinical trials, with pilot program selection criteria disseminated in mid-2026, could alter how isotopic data is utilized in drug development. If real-time monitoring becomes standard, the demand for rapid-turnaround analytical systems may increase, favoring certain technological architectures over others.
These regulatory currents create a complex environment for market participants. Organizations must not only select the right technology but also ensure that their entire operational chain meets evolving standards. Our report includes a dedicated section on these dynamics, helping readers anticipate compliance costs and regulatory risks associated with different market segments.
Strategic Imperatives for Decision Makers
As we look toward the forecast period ending in 2032, several strategic imperatives emerge for stakeholders in the stable isotope analyzer market. First, there is the need for agility in procurement. With a CAGR of 8.7 percent, the market is expanding fast enough to create supply constraints or lead time variations. Strategic buyers should engage with vendors early to secure capacity and negotiate favorable terms, particularly for high-demand systems.
Second, investment in workforce training and expertise is crucial. As instruments become more integrated and software-driven, the skill set required to operate them and interpret data is evolving. Companies that invest in training their analytical staff will gain a competitive edge in data quality and throughput.
Third, monitoring the competitive landscape is essential. The recent product announcements from Elementar, Sercon, and Cambridge Isotope Laboratories demonstrate that innovation is active. Keeping abreast of these developments allows organizations to time their technology refreshes effectively, avoiding the trap of owning obsolete equipment while competitors leverage newer capabilities.
Finally, understanding the geographic nuances of the market is vital. While specific regional revenue splits are part of our detailed proprietary data, it is clear that different regions prioritize different applications. North American markets may lean heavily toward pharmaceutical and high-end research applications, while European demand is closely tied to regulatory compliance in food and environmental sectors. Asia Pacific represents a growing frontier where industrialization and research investment are driving new demand. A nuanced understanding of these regional dynamics is necessary for global strategy formulation.
Conclusion: Accessing Deep-Dive Intelligence
The Stable Isotope Analyzer Market is at an inflection point where technical maturity meets regulatory complexity and sustained growth. The journey from 2026 to 2032 will be defined by how well organizations can navigate the interplay between hardware capabilities, application requirements, and compliance mandates. The data points outlined in this preview—from the historical resilience of the market to the specific innovations of key competitors—only scratch the surface of the intelligence available in our full report.
PW Consulting's comprehensive study offers a granular breakdown of market sizes, segmentation splits, competitive profiles, and risk analyses that are essential for high-stakes decision-making. We have intentionally withheld specific segmentation percentages and detailed regional revenue figures in this overview to preserve the integrity of our proprietary analysis. To access the complete dataset, including exact market values by region, type, and application, as well as deep-dive competitor benchmarking and strategic recommendations, we invite you to explore the full report on our website.
In a world where precision is currency, having the most accurate market intelligence is the first step toward securing your organization's future. Let this preview serve as the catalyst for a deeper engagement with the data that will drive your strategy forward.
For detailed analysis of this topic, please visit the official page: Stable Isotope Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Walk Through Sole Cleaner Market Geographic Segmentation, Statistical Forecast & Industry Analysis to 2033
By Arjun, 2026-09-07
Overview
The Walk Through Sole Cleaner Market encompasses advanced cleaning systems designed to efficiently sanitize footwear in various industrial, commercial, and institutional settings. These systems are vital for maintaining hygiene standards, preventing cross-contamination, and ensuring compliance with health and safety regulations. Core functionalities include automated cleaning processes, touchless operation, and customizable cleaning cycles, supporting industries such as healthcare, manufacturing, food processing, and logistics.
The purpose of the walk through sole cleaner is to provide a seamless and effective method for disinfecting footwear at entry points. Its importance lies in reducing contamination risks while streamlining workforce entry procedures. The market for walk through sole cleaner plays a critical role in supporting modern industries or technologies that prioritize hygiene and operational efficiency, making it an integral component of facility management.
Market Size and Growth
The current estimated market value for the walk through sole cleaner market is approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 2.8 billion, with a compound annual growth rate (CAGR) of approximately 9.4%. Growth drivers include increasing health and safety regulations, rising awareness of contamination control, and expanding industrial automation.
Enhanced focus on hygiene standards, especially post-pandemic, is fueling demand across sectors. Technological advancements and integration with smart building systems further bolster market expansion, making walk through sole cleaner solutions a strategic investment for future-proof facilities.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI3619
Key Drivers
- Stringent hygiene regulations across industries
- Rising awareness of contamination risks
- Increasing adoption in healthcare and food sectors
- Growth in industrial automation and smart facility solutions
- Expansion of industrial and commercial infrastructure
Restraints
- High initial capital investment
- Technical complexity in integration
- Limited awareness in emerging markets
- Maintenance and operational costs
- Regulatory delays in some regions
Segmentation
- By Type: Manual, Automatic, Semi-Automatic
- By Deployment: Indoor, Outdoor
- By Enterprise Size: Small, Medium, Large
- By End User: Healthcare, Food & Beverage, Manufacturing, Logistics, Others
- By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong demand driven by stringent health regulations and technological adoption in healthcare and manufacturing sectors. Europe’s focus on hygiene compliance and industrial automation supports steady growth. Asia-Pacific is witnessing rapid adoption fueled by expanding industrial infrastructure and urbanization. Latin America’s market growth is primarily driven by food processing and healthcare sectors. Middle East & Africa show emerging demand, with opportunities linked to industrial development and infrastructure projects.
Opportunities
- Expansion into emerging markets with rising industrial activity
- Integration of IoT and AI in cleaning systems
- Development of eco-friendly and energy-efficient solutions
- Increasing adoption in healthcare and pharmaceutical industries
- Adoption of smart facility management technologies
Key Companies
CTS Corporation, CleanTech Solutions, EcoClean Systems, Germfree Technologies, HygienePro, InnovateClean, Johnson Controls, Karcher, Nilfisk, Tennant Company, Vikan, Weber
Conclusion
The overall outlook for the walk through sole cleaner market remains positive, with long-term growth potential supported by increasing hygiene standards and technological innovation. As industries continue to prioritize contamination control and operational efficiency, the strategic importance of these cleaning solutions will grow. The market is poised for sustained expansion, driven by emerging regions and evolving industry requirements, making it a vital component of modern facility management.
Related Reports
Industrial Rollers Market , Size Share and Analysis | Report 2033
Double Liquid Dispenser Market , Size Share and Analysis | Report 2033
Anilox Cleaning Machines Market , Size Share and Analysis | Report 2033
Thermocouple Calibration Furnace Market , Size Share and Analysis | Report 2033
Tsv Copper Filled Plating System Market , Size Share and Analysis | Report 2033
Unmanned Pesticide Control Robot Market , Size Share and Analysis | Report 2033
Co2 Recovery Unit Market , Size Share and Analysis | Report 2033
New Energy Orchard Plant Protection Robot Market , Size Share and Analysis | Report 2033
Military Powered Exoskeleton Market , Size Share and Analysis | Report 2033
Dual Winding Motor Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/